MONEY & BUDGETING · 17 min read
HOW TO BUDGET WHEN MONEY IS TIGHT
A practical way to build a monthly budget on a low income: see what you really have, protect the costs that matter most and stop planning around money that never arrives.
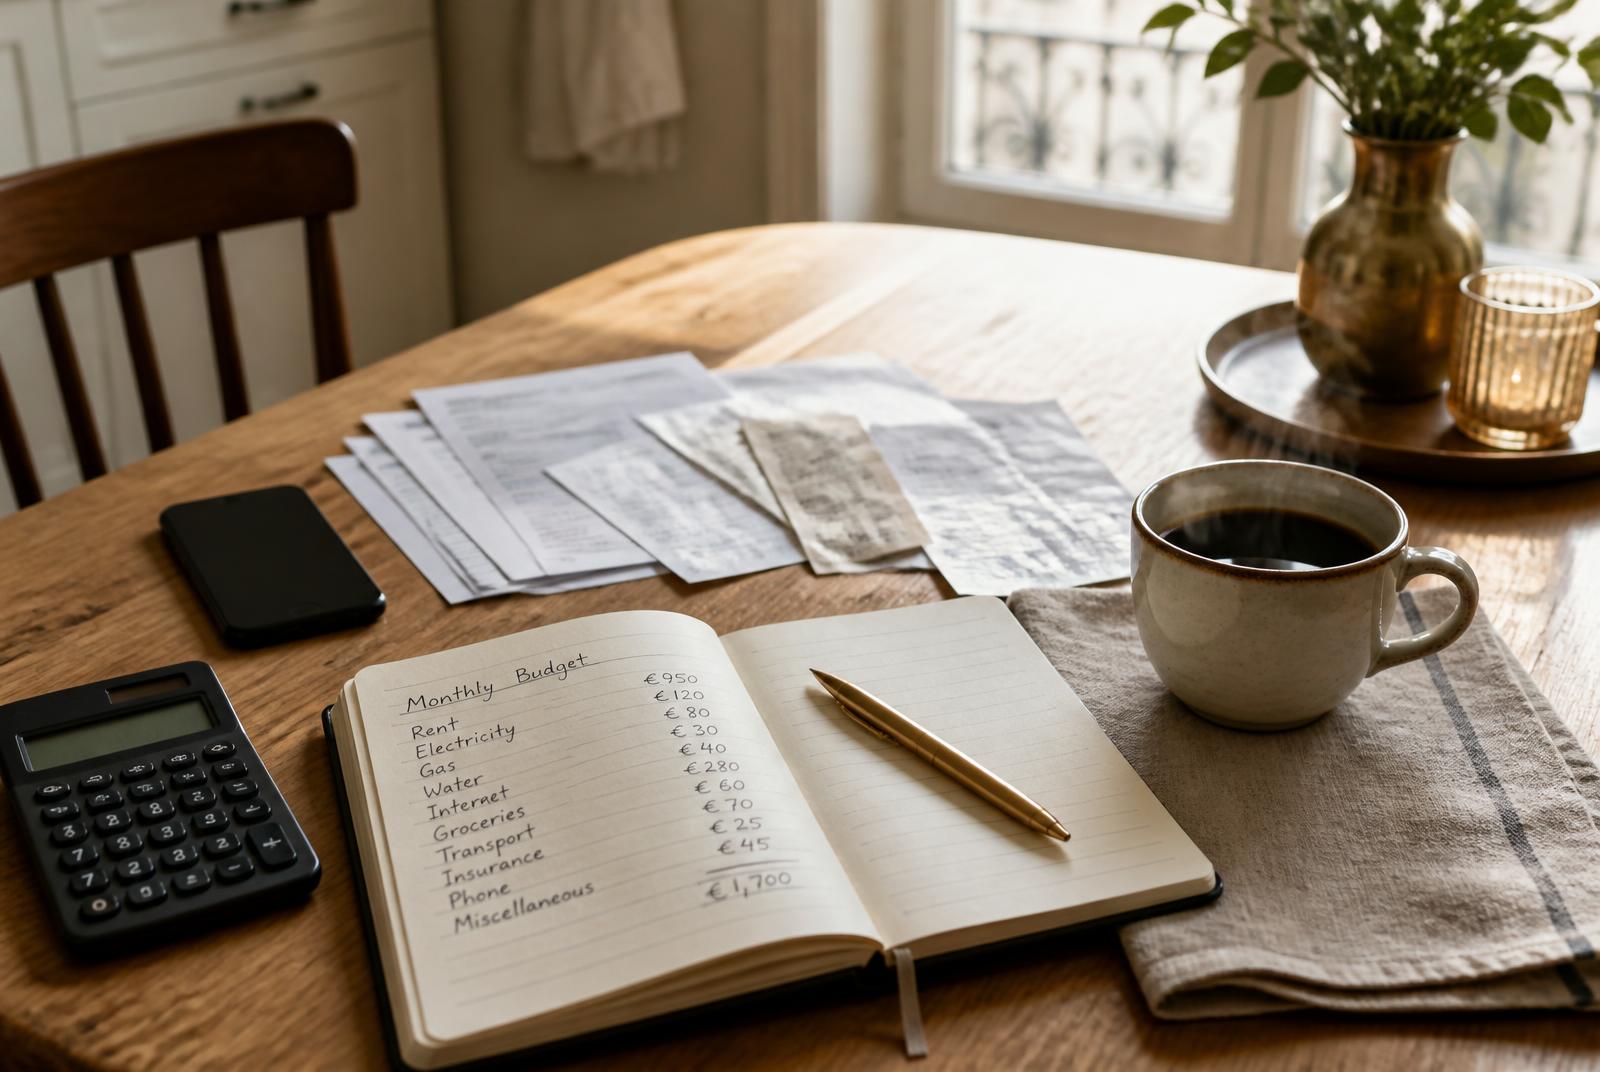
Most budgeting advice assumes there is spare money to move around. When money is tight there is no spare, so every template that starts with percentages and savings goals falls apart in the first week.
A tight budget works differently. It is not a plan for the money you wish you had. It is a short, honest map of the money that actually reaches your account, the costs that keep your life running, and what is left after those two things meet.
This guide walks through that in order. No targets, no promises about how long anything takes, and no assumption that your income covers everything. If it does not, there is a section for that too.
WHY BUDGETING FEELS HARD WHEN MONEY IS TIGHT
When there is room in your budget, mistakes are absorbed quietly. A forgotten subscription or a bigger grocery week costs you a little comfort and nothing else. When money is tight, the same mistake turns into a failed payment, a fee, or a week of eating from the cupboard.
That is why tight budgets feel stressful in a way ordinary budgeting does not. The margin for being slightly wrong is gone, so every estimate has to be closer to real. And most standard budget advice was written for people who still have that margin.
- Percentage based rules assume money is left over after the essentials.
- Annual and quarterly costs land in months that were already full.
- Irregular income makes a fixed monthly plan wrong by default.
- One missed payment can add costs that make the next month harder.
- Advice that starts with saving skips the part you are actually stuck on.
A TIGHT BUDGET IS A DIFFERENT TOOL
When money is tight, a budget is not there to optimise your spending. It is there to tell you which costs are covered, which are not, and how much time you have before something breaks.
That is a smaller job than most budget templates try to do, and it is the one that actually helps.
START WITH THE MONEY YOU ACTUALLY HAVE
Every realistic budget starts with a number you can verify, not one you remember. Open your accounts and write down what is there today, then write down the next money coming in and the date it arrives.
If your income changes month to month, do not average it upwards. Use a low but realistic figure from a recent month, and treat anything above it as a bonus you can decide about later. Planning on your best month is the fastest way to make a budget fail.
- Current balance in every account you use, including any overdraft you are inside.
- Next income date and the amount you can genuinely count on.
- Any money already spoken for, such as a payment that has not cleared yet.
- Income that only sometimes arrives, listed separately and not counted on.
- Benefits, allowances or support payments and the dates they land.
IF OPENING YOUR ACCOUNTS IS THE HARD PART
Plenty of people know their budget is broken and avoid looking at it, which makes the numbers worse and the fear larger. If that is where you are, read how to stop avoiding your bank account first and come back to this once you have looked.
You do not need to feel calm about the numbers. You just need them written down.
LIST YOUR ESSENTIAL COSTS FIRST
On a tight budget, the order you list costs in matters more than the total. Start with the costs that keep your housing, your energy, your food and your ability to work or study in place. Everything else waits until those are on the page.
Write each one with its amount and its date. A cost you know the date of is a cost you can plan around. A cost you only remember when it leaves your account is the one that breaks the month.
- Rent or mortgage, plus anything tied to keeping your home.
- Energy, water and any fixed utility payment.
- Food and basic household supplies.
- Transport you need to reach work, study or care.
- Insurance you are legally required to hold or genuinely depend on.
- Medication, care costs and anything health related you cannot skip.
- Phone and internet if you need them for work, benefits or contact.
ESSENTIAL DOES NOT MEAN UNCHANGEABLE
Essential means the category cannot go, not that the amount is fixed. Food is essential; the size of your food bill is not. Energy is essential; your tariff might be negotiable.
Keep that distinction in mind now, and act on it later in the section on creating more room.
SEPARATE ESSENTIAL SPENDING FROM FLEXIBLE SPENDING
Once the essentials are listed, everything else goes on a second list. Flexible spending is not the same as pointless spending. It is spending where you control the timing, the amount or whether it happens at all this month.
The point of the split is not to shame the second list. It is to know exactly where your options are before you need them, so that a difficult week does not turn into a random decision made at midnight.
- Takeaways, coffee out, snacks and convenience buying.
- Clothes, homeware and anything you can delay without consequence.
- Streaming, apps, gaming and other optional subscriptions.
- Gifts, social plans and days out.
- Anything bought on impulse in the last month.
USE REAL DATA, NOT ESTIMATES
Almost everyone underestimates flexible spending, usually by a wide margin, because small purchases are forgettable by design. Scroll one full month of transactions and sort them rather than guessing.
The free Spending Check does that sorting for you in a few minutes and keeps everything on your own device.
LOOK AT YOUR MONTHLY COMMITMENTS
Commitments sit between essential and flexible: contracts, payment plans, instalments and subscriptions you signed up for once and have paid ever since. They are the part of a tight budget people most often forget to review.
List every one with the amount, the payment date, the notice period and whether you are still inside a minimum term. Some can be cancelled today. Some cannot, but knowing which is which stops you counting on money that is already committed.
- Phone, internet and any device contract.
- Insurance policies, including ones you may be doubling up on.
- Buy now pay later plans and instalments on past purchases.
- Loan and card repayments, with their minimum amounts.
- Memberships, subscriptions and anything renewing annually.
ANNUAL COSTS BELONG IN THE MONTHLY PICTURE
A yearly insurance premium or road tax bill is not an emergency. It is a known cost with a known date that nobody wrote down.
List each annual cost with its month. Even if you cannot set money aside for it yet, you will see it coming instead of meeting it by surprise.
DECIDE WHAT NEEDS YOUR ATTENTION FIRST
With everything on one page, you can rank rather than react. On a tight budget, attention usually goes first to whatever has the most serious consequence if it is not paid, and to whatever is already going wrong.
What that means in practice depends on the type of debt, the creditor, the rules where you live and your own circumstances. Housing and energy arrears, tax debts and court enforced payments tend to carry heavier consequences than ordinary consumer credit in many countries, but that is not a universal rule and it is not advice about your situation. If payments are already being missed, get the ranking confirmed by official debt advice in your country rather than deciding alone.
- What happens if this is not paid, and how quickly?
- Is this account already behind, or heading that way this month?
- Is there a deadline, a notice or a letter attached to it?
- Would contacting this creditor early change what happens next?
- Is this a debt where local rules give the creditor extra powers?
NO SINGLE REPAYMENT METHOD IS UNIVERSALLY RIGHT
You will read confident advice telling you to always clear the smallest balance first, or always the highest interest rate first. Both approaches work for some people and are wrong for others, and neither takes account of which creditor can cause you the most trouble.
Build the overview before choosing a method. How to organise your debts when you feel overwhelmed walks through that overview step by step, and the free Debt Reset puts your balances and payments into one view.
BUILD A BUDGET AROUND REALITY
Now write the plan itself. Income at the top using the conservative figure, essentials next in date order, commitments after that, and whatever remains at the bottom. That remainder, positive or negative, is the real answer your budget gives you.
Keep it to one page. A tight budget that takes half an hour to update will not be updated, and an out of date budget is worse than a rough one because you trust it while it is wrong.
- Use one month at a time, not a yearly projection.
- Order costs by date so you can see the gaps between income and payments.
- Give flexible spending a single line rather than ten categories.
- Leave a small buffer line for the thing you have not thought of.
- Write the figure that is left after everything, even when it is negative.
PUT THE NUMBERS SOMEWHERE THAT DOES THE MATHS
The free Money Reset turns your income, fixed costs and spending into one clear picture in a few minutes and shows what is left. Nothing leaves your device.
If you would rather use paper or a spreadsheet, that is equally fine. The tool matters far less than having one version of the numbers instead of four.
FIND SMALL WAYS TO CREATE MORE ROOM
Once the plan exists, you can look for room without guessing where it might be. On a tight budget the useful savings are usually recurring ones, because they repeat every month without you doing anything again.
Work through the recurring costs first, then the flexible list. A contract renegotiated once beats a month of cutting small treats, and it costs you nothing in daily life.
- Cancel subscriptions you have not deliberately used in the last month.
- Check whether your energy, phone or insurance contract can be changed or switched.
- Ask existing providers what they can do before moving anywhere.
- Plan food around a short list and what is already in the cupboard.
- Set a single weekly amount for flexible spending instead of deciding daily.
- Move any payment date that lands awkwardly before your income arrives.
GO DEEPER ON THE RECURRING COSTS
How to lower your monthly expenses works through housing, energy, insurance, subscriptions and food one category at a time.
If the problem is that there seems to be nothing left to cut at all, how to save money when you feel like you have nothing left covers what to do from there.
Some links on this page may be affiliate links. If you use one, we may earn a small commission at no additional cost to you. Not every link is an affiliate link, and we never take gambling or betting partnerships. Read the full disclosure
OUR GUIDE
Finding Your Way Back
A calm, practical digital guide for rebuilding your money, your habits and your direction step by step. Download instantly after payment.
€9.99 · instant download
WHAT IF YOUR INCOME DOES NOT COVER YOUR ESSENTIAL COSTS?
Sometimes the honest answer at the bottom of the page is a negative number, and no amount of budgeting closes it. That is not a budgeting failure. It is a gap between income and essential costs, and it needs a different set of actions.
Budgeting still has a job here: it tells you the size of the gap, which is the single most useful figure to have when you contact anyone for help. Go in with a number rather than a feeling.
- Check whether benefits, allowances or local support schemes apply to you.
- Contact creditors before a payment fails and ask what arrangements exist.
- Ask about payment plans, pauses or hardship arrangements in writing.
- Get your situation assessed by official debt advice in your country.
- Look at whether additional income is realistic given your health and time.
- Ask about food, energy or housing support locally rather than assuming there is none.
EARLY CONTACT USUALLY CHANGES YOUR OPTIONS
Creditors generally have more room to agree something before an account is in arrears than after it has been passed on. Contacting them early is uncomfortable and it is almost always worth it.
Our get help page points toward official services, and how to start over financially covers rebuilding once the immediate pressure eases.
HOW TO BUDGET WITHOUT CHECKING YOUR MONEY CONSTANTLY
When money is tight, many people either avoid their accounts entirely or check them ten times a day. Both come from the same place, and neither gives you new information.
Structure replaces checking. If your bills leave from one account and your spending happens from another, you can see where you stand at a glance instead of doing mental arithmetic every time you buy something.
- Keep bill money in a separate account from spending money.
- Move payment dates so they follow your income rather than precede it.
- Set a fixed weekly amount for flexible spending and spend from that.
- Turn on payment notifications so you learn about problems immediately.
- Check properly once a week at a set time instead of constantly.
MAKE THE STRUCTURE DO THE WORK
Every rule you set once is a decision you do not have to make again under pressure. That matters more on a tight budget than on a comfortable one.
If the overwhelm rather than the arithmetic is the main problem, how to get control of your money without feeling overwhelmed takes the same ground from that angle.
A FIVE MINUTE TIGHT BUDGET RESET
When the full process feels like too much, do the short version. Five minutes will not give you a complete budget, but it will move you from guessing to knowing where you stand this week.
Do it with your bank app open and something to write on.
- Minute one: write down your current balance across every account.
- Minute two: write your next income date and the amount you can count on.
- Minute three: list the payments due before that date, with their amounts.
- Minute four: subtract those payments from the balance and write the result.
- Minute five: if the result is negative, write down which one payment you will contact someone about today.
REPEAT IT WEEKLY
This short version works well as a weekly habit even after your full budget exists. It catches problems while they are still small enough to solve with a phone call.
Five minutes a week is also short enough to keep doing in a bad month, which is exactly when it matters most.
HOW TO STAY CONSISTENT WITH A TIGHT BUDGET
Budgets rarely fail because the numbers were wrong. They fail because they were built for a perfect month, and a normal month arrived instead. A car repair, a birthday, a slow week at work, and the plan is abandoned rather than adjusted.
Consistency comes from expecting that and building a plan that can be corrected. A budget you update is working. A budget you abandon after one bad week never had room in it to begin with.
- Adjust the plan when reality changes instead of starting a new one.
- Keep a small buffer line so one surprise does not break everything.
- Do a short weekly check and one longer monthly update.
- Track whether costs are covered rather than whether you were disciplined.
- Rebuild the budget whenever your income or your bills change.
MEASURE THE RIGHT THING
On a tight budget, success is not a number saved. It is essentials covered, nothing new going into arrears, and knowing what is coming.
If those three things are true this month, the budget is doing its job, whatever the balance looks like.
WHEN TO GET EXTRA HELP
Budgeting has limits, and reaching them is common rather than unusual. If your essential costs exceed your income, if you are behind on payments, or if creditors have started to escalate, the next step is outside advice rather than another spreadsheet.
Official debt advice in your country can tell you what applies to your situation, which is something no article can do. It is usually free, and going early gives you more options than going late.
- Your income does not cover essential costs, month after month.
- You are behind on rent, mortgage, energy or tax payments.
- Debt collection or enforcement has started.
- You are borrowing to make repayments on other borrowing.
- The situation is affecting your health, sleep or ability to work.
WHAT TO BRING
Take your income figure, your list of essential costs, your list of debts with creditors and amounts, and any letters you have received. The overview you built here is most of what an adviser will ask for.
Our get help page points toward appropriate services, and the wider guide to getting your finances back on track covers the full picture.
PRACTICAL TIGHT BUDGET CHECKLIST
Work through this in order. You can stop after any step and pick it up later; the list stays useful either way.
- Write down the balance of every account you use today.
- Write your next income date and a conservative amount.
- List every essential cost with its amount and payment date.
- List every contract, subscription and instalment, with notice periods.
- List every debt with creditor, balance and minimum payment.
- Scroll one full month of transactions and total your flexible spending.
- Mark any account that is already behind or close to it.
- Rank what needs attention first based on consequences, not size.
- Write the one page plan: income, essentials, commitments, what is left.
- Cancel or renegotiate at least one recurring cost this week.
- Set one weekly amount for flexible spending.
- Book a five minute check at the same time every week.
- If the bottom line is negative, contact official debt advice this week.
IF YOU ONLY DO THREE THINGS
Write down your real income, list your essential costs with dates, and find out what is left. Everything else in this guide builds on those three numbers.
Start there today and let the rest follow when you have the energy for it.
FREQUENTLY ASKED QUESTIONS
Short answers to the questions that come up most often about budgeting on a tight income.
HOW DO I BUDGET WHEN I HAVE VERY LITTLE MONEY?
Start smaller than a standard budget. Write down what is in your accounts, what income is coming and when, and the essential costs due before then. That short version tells you whether this period is covered, which is the question that matters when money is tight. Build the fuller monthly plan afterwards, using a conservative income figure rather than your best month.
WHAT SHOULD I PAY FIRST WHEN MONEY IS TIGHT?
There is no single correct order that applies to everyone. Payment priorities depend on the type of debt, the creditor, the consequences of not paying and the rules where you live. In many countries, costs tied to keeping your home, your energy supply and legally enforced payments carry heavier consequences than ordinary consumer credit, but you should have that confirmed for your situation. If you are already missing payments, contact official debt advice in your country before deciding what to skip.
HOW CAN I REDUCE SPENDING WHEN I ALREADY FEEL LIKE I SPEND VERY LITTLE?
Look at recurring costs rather than daily ones. Contracts, insurance, subscriptions and tariffs are where room is usually left when the flexible spending is already low, and changing one of those pays off every month without affecting your daily life. Scroll a full month of transactions first, because the costs people forget are almost always the automatic ones rather than the visible ones.
WHAT IF MY INCOME DOES NOT COVER MY ESSENTIAL EXPENSES?
Then budgeting will not close the gap, and it is not supposed to. Work out the size of the shortfall, check whether benefits, allowances or local support apply to you, contact creditors before payments fail to ask about arrangements, and have your situation assessed by official debt advice in your country. Going early usually leaves more options open than waiting until accounts are in arrears.
HOW OFTEN SHOULD I REVIEW A TIGHT BUDGET?
A short weekly check and one longer monthly update works for most people, plus a full rebuild whenever your income or your bills change. On a tight budget the weekly check matters more than on a comfortable one, because problems become expensive quickly. Once the information exists, each check takes a few minutes.
TURN YOUR BUDGET INTO REAL NUMBERS
The free Money Reset turns your income, fixed costs and spending into one clear picture in a few minutes, so you can see what is left and what needs attention first. Everything stays on your own device.
Some links on this page may be affiliate links. If you use one, we may earn a small commission at no additional cost to you. Not every link is an affiliate link, and we never take gambling or betting partnerships. Read the full disclosure
This article is general information and education. It is not personal financial, tax or legal advice, and rules differ by country. If you have serious payment problems, contact official debt advice or a qualified financial adviser near you.
NEXT STEP
Once the budget exists, the next question is usually where the everyday money goes. The Spending Check answers that in a few minutes.
OPEN THE SPENDING CHECKCONTINUE FROM HERE
Two natural next steps, whichever chapter you are working on.
READ NEXT
HOW TO GET YOUR FINANCES BACK ON TRACK
The full guide: overview, bills, debts and a plan you can keep going.
HOW TO LOWER YOUR MONTHLY EXPENSES
Go through every recurring cost and find room that returns each month.
HOW TO ORGANISE YOUR DEBTS WHEN YOU FEEL OVERWHELMED
One overview, clear priorities and a plan that fits your income.