MONEY & CONTROL · 15 min read
HOW TO GET CONTROL OF YOUR MONEY WITHOUT FEELING OVERWHELMED
A calm order of steps for anyone whose finances feel like too much: see the numbers, pick a priority and build one plan you can actually follow.
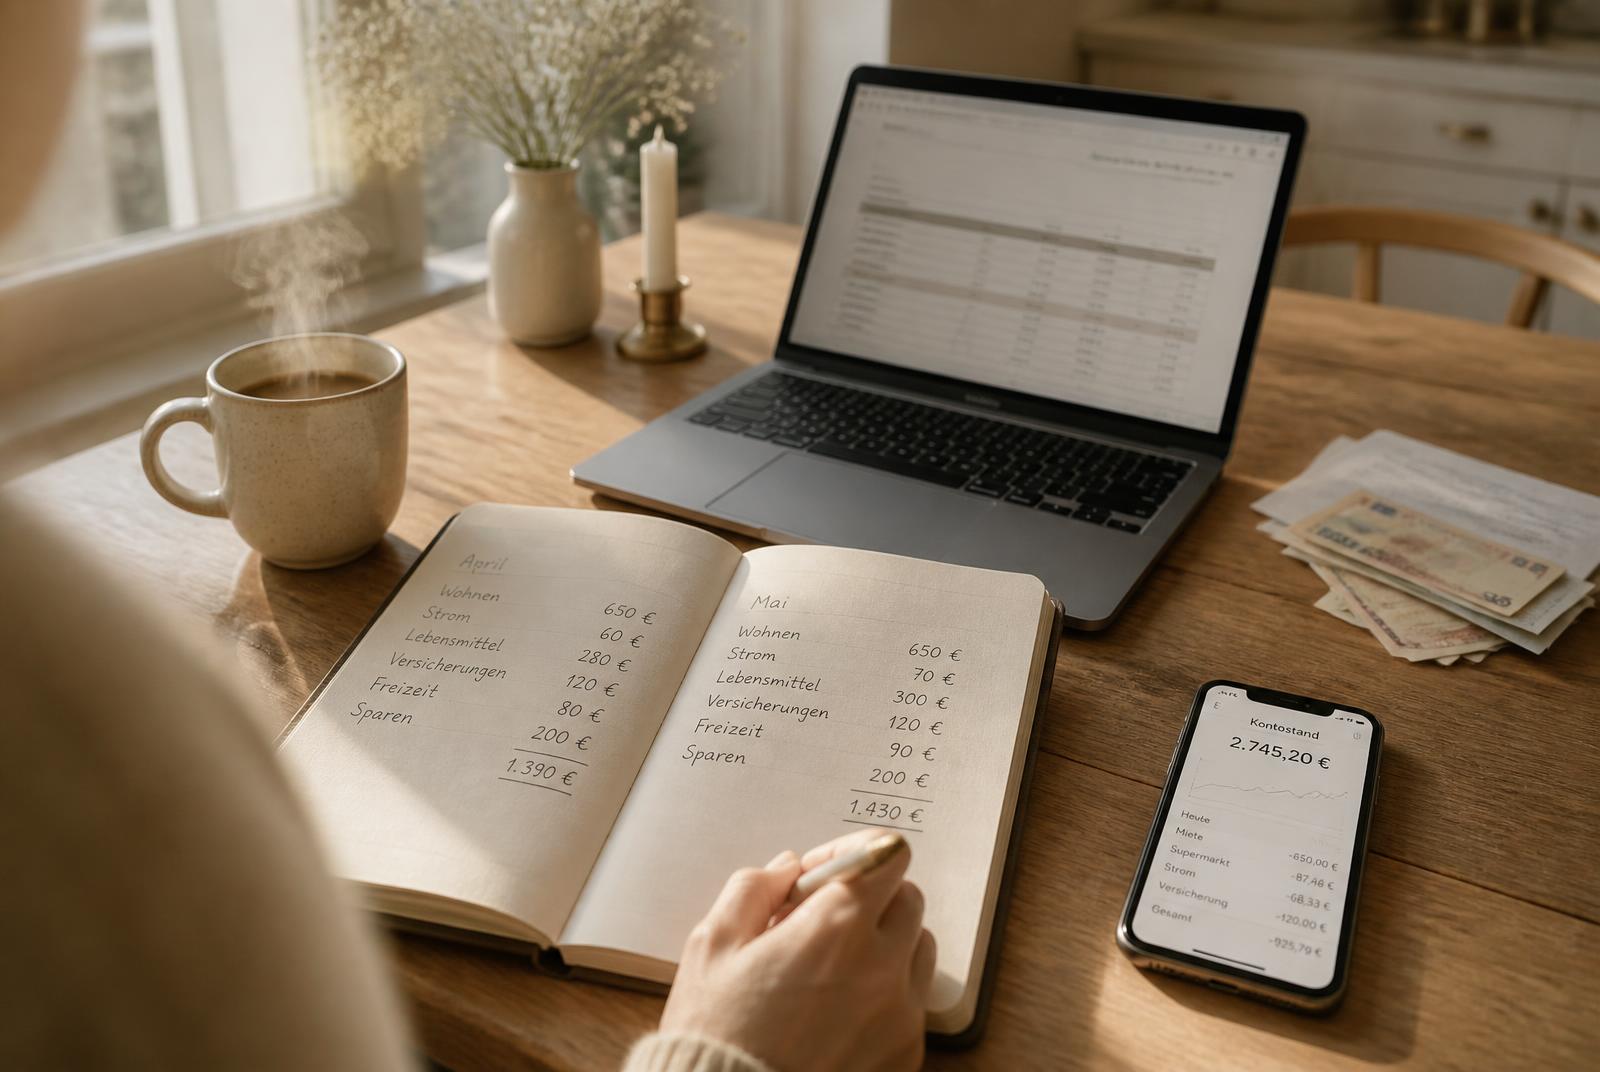
Money rarely feels overwhelming because of one number. It feels overwhelming because there are many numbers, they live in different places, and none of them are written down together. Every time you think about them, you start from nothing.
This guide fixes that in order. First one picture of your situation, then a short list of priorities, then one monthly plan that fits your real income rather than an ideal version of it.
There are no targets, no percentages and no promises about how long anything takes. Your income, your bills and the rules where you live all differ. What stays the same is the order: see it, sort it, decide, then act on one thing at a time.
WHY MONEY CAN FEEL SO OVERWHELMING
Financial overwhelm is usually an information problem before it is a money problem. Your rent is in one app, your card spending in another, your subscriptions on a card you barely check and your debts in letters you have not opened. Nothing is hidden, but nothing is visible either.
So your brain does what it does with any unclear threat: it estimates. Estimates in money are almost always worse than reality in some places and better in others, and the not knowing is what keeps the feeling going.
- The numbers exist in several places and never in one view.
- Some costs only appear once a year, so they always feel like a surprise.
- Debt letters carry deadlines you cannot see until you open them.
- Every decision feels urgent because none of them are ranked.
- You keep re-thinking the same problem instead of writing it down once.
OVERWHELM IS NOT A CHARACTER FLAW
Managing money in a normal modern life means tracking a dozen contracts, several payment methods and irregular income. Very few people are taught how, and nobody keeps that in their head reliably.
The way out is not more discipline. It is a shorter list and a place to keep it.
STOP TRYING TO SOLVE EVERYTHING AT ONCE
The most common reason people give up on their finances is that they try to fix everything in one weekend. Budget, debts, savings, subscriptions, income, all at the same time. That is too many decisions for one sitting, so nothing gets finished.
Pick a sequence instead. Overview comes first because every other decision depends on it. Nothing else needs your attention until you can see the picture.
- Write down what you will not deal with today, so you can stop carrying it.
- Finish one step completely rather than starting five.
- Accept a rough number now instead of waiting for a perfect one.
- Set a time limit for the first session, for example one hour.
- Keep everything in one place, on paper or in one file.
ONE DECISION AT A TIME
If your finances have been left alone for a while, the first session is mostly reading and writing, not deciding. That is normal and it is progress.
If even opening your banking app is the part that stops you, start with how to stop avoiding your bank account and come back here afterwards.
START WITH THE NUMBERS YOU HAVE TODAY
Control starts with a snapshot, not a plan. What is in your accounts right now, what is owed, and what is due in the next few weeks. That is the whole first step.
Use real figures from your bank rather than memory. Memory rounds down on spending and rounds up on income, which is exactly the wrong direction.
- Current balance in every account you use.
- Anything owed on cards, overdrafts, loans or payment plans.
- Payments due in the next two weeks and their dates.
- Any income you know is coming and when it lands.
- Anything you are behind on, written down plainly.
USE ONE TOOL, NOT FIVE
The free Money Reset turns your income, fixed costs and spending into one picture in a few minutes, and everything stays on your own device.
A notebook works just as well. What matters is that there is one place where the full picture lives, so you never have to rebuild it from memory again.
KNOW WHAT COMES INTO YOUR ACCOUNT
Most people can name their salary but not their actual monthly income. Those are different numbers once you include benefits, allowances, side income, refunds and any irregular work.
If your income varies, do not use the good months. Use the lowest realistic month as your planning number, and treat anything above that as extra you can assign later.
- Net pay after tax and deductions, per payment date.
- Benefits, allowances or support you receive where you live.
- Side income, freelance work or irregular payments.
- Money from other people in your household that covers shared costs.
- Refunds or annual payments that arrive at fixed moments.
WHEN INCOME IS IRREGULAR
Look back over the last six months if you can and note the lowest total. Planning on that figure means a weak month is uncomfortable rather than a crisis.
Write down the dates too. Timing causes more missed payments than totals do.
KNOW WHAT GOES OUT
Now the other side. Go through two or three months of bank activity and list everything that left your account, including the small repeating amounts that never feel like real spending.
Do not judge anything yet. This step is only about seeing the full total, because the total is the number every later decision depends on.
- Housing: rent or mortgage, service charges, local taxes.
- Utilities and contracts: energy, water, internet, phone.
- Insurance of every kind, including cover you forgot you had.
- Transport: fuel, public transport, road tax, parking, maintenance.
- Debt payments, minimum payments and payment plans.
- Subscriptions, memberships and app charges.
- Groceries and everyday household spending.
ADD THE COSTS THAT ARRIVE ONCE A YEAR
Annual insurance, road tax, birthdays, holidays and school costs are real monthly costs, they just arrive in one lump. Divide each by twelve and include the monthly figure.
The free Spending Check sorts flexible spending into patterns quickly if the everyday side is where the picture is unclear.
SEPARATE WHAT IS ESSENTIAL FROM WHAT CAN CHANGE
With the full list in front of you, split it in two. Essential is what keeps your home, health, food, transport to work and safety in place. Everything else can change, even if it has been running for years.
This is not about cutting the second column. It is about knowing which costs are choices, so that when you need room you know where it can come from.
- Essential: housing, energy, food, insurance you must hold, transport to work, care costs.
- Can change: subscriptions, memberships, delivery, upgrades, extras.
- In between: phone tariff, car use, gym, some insurance. Necessary in some lives, optional in others.
- Keep at least one thing you enjoy in the plan. A budget with nothing in it does not survive a month.
FIXED COSTS ARE OFTEN THE BIGGER OPPORTUNITY
Flexible spending needs daily attention. A lower contract needs one phone call and then keeps working every month afterwards.
If this is where your pressure sits, how to lower your monthly expenses goes through each bill in turn, and how to save money when you feel like you have nothing left starts from the point where it feels like nothing is left to cut.
DECIDE WHAT NEEDS YOUR ATTENTION FIRST
Not everything on your list matters equally this month. Some costs have serious consequences if they are missed, and some are simply annoying. Ranking them is what turns a long list into a short plan.
Look at consequences rather than amounts. A small missed payment with a hard deadline can cost more than a large one with flexibility.
- What happens if this is paid late, and how quickly?
- Is anyone already chasing this, and at what stage?
- Does missing it affect your home, energy, health cover or work?
- Is there a deadline attached that you can actually see in writing?
- Can this creditor be contacted before something goes wrong?
WHY THERE IS NO UNIVERSAL ORDER
Which debt or bill should come first depends on the type of debt, the creditor, the consequences of nonpayment and the rules in your country. Any article that gives you one fixed order is guessing about your situation.
If debts are the heaviest part, put them into one overview first using how to organise your debts when you feel overwhelmed and the free Debt Reset. If payment problems are serious, check the order with official debt advice or a qualified adviser where you live before deciding.
CREATE ONE SIMPLE MONTHLY MONEY PLAN
A plan is one page: income, essential costs, priority payments, everyday spending and whatever is left. If it needs a spreadsheet with tabs, it will not survive a busy month.
Build it around your payment dates rather than the calendar month. Most money problems are timing problems, not total problems.
- Write the income date at the top and the payment dates underneath.
- Move automatic payments to just after income arrives where your bank allows it.
- Give everyday spending its own amount so it stops competing with bills.
- Leave a small buffer line for the things that always come up.
- Give any leftover amount one job rather than four.
PLAN FOR THE MONTH YOU ACTUALLY HAVE
A plan built on your best month fails in your average month. Build it on the low version and treat extra income as a bonus you assign consciously.
If you are rebuilding from a difficult period, how to start over financially covers the wider reset, and the full guide is how to get your finances back on track.
WHAT IF YOUR INCOME DOES NOT COVER EVERYTHING?
Sometimes you finish the overview and the numbers simply do not meet. That is a real answer, not a failure of planning, and it changes what you do next.
From that point the useful moves are about support, agreements and income rather than tighter budgeting.
- Check whether allowances, benefits or local schemes apply to you.
- Contact creditors before a payment fails rather than after.
- Ask whether a temporary lower payment or a payment date change is possible.
- See whether any small additional income is realistic right now.
- Get your situation reviewed by official debt support in your country.
ASKING EARLY CHANGES YOUR OPTIONS
Most organisations have more room to arrange something before a payment is missed than after it has gone to collection. Contacting them early is a practical move, not an admission of anything.
Support, rules and available schemes differ by country, so use the official services where you live. Our help page points you toward the right kind of support.
MAKE YOUR MONEY EASIER TO MANAGE
Control is much easier when your setup does the remembering for you. Most of the effort people spend on money is spent compensating for a messy structure.
Change the structure once and the daily effort drops for good.
- Keep bills and everyday spending in separate accounts if your bank allows it.
- Automate fixed payments for the day after income arrives.
- Keep any buffer away from your everyday card.
- Turn on notifications for payments and low balances.
- Cancel payment methods you no longer want to use.
- Keep one folder, physical or digital, for letters and contracts.
MAKE THE RIGHT THING THE DEFAULT
If money for bills is never in the account you spend from, you do not have to resist spending it. The structure does that work instead of you.
Every automation you set up is one decision you never have to make again.
Some links on this page may be affiliate links. If you use one, we may earn a small commission at no additional cost to you. Not every link is an affiliate link, and we never take gambling or betting partnerships. Read the full disclosure
OUR GUIDE
Finding Your Way Back
A calm, practical digital guide for rebuilding your money, your habits and your direction step by step. Download instantly after payment.
€9.99 · instant download
A FIVE MINUTE MONEY RESET
When the whole picture feels like too much, shrink the task. Five minutes is short enough that you can do it today and still get something real from it.
This is not the full overview. It is the smallest version that moves you from guessing to knowing.
- Minute one: open your main account and read the balance without reacting to it.
- Minute two: write down your next income date and amount.
- Minute three: list the payments due before that date.
- Minute four: mark the one payment with the most serious consequence.
- Minute five: decide the single next action and write it down with a day attached.
REPEAT IT RATHER THAN PERFECT IT
Doing this once tells you where you stand. Doing it weekly is what keeps you there, and it stays short once the information is already written down.
If five minutes still feels like too much on a given day, do minute one only. Looking is the step that breaks the cycle.
HOW TO STAY IN CONTROL WITHOUT THINKING ABOUT MONEY ALL DAY
The point of getting control is to think about money less, not more. Once the plan exists, your job is maintenance rather than constant monitoring.
Give it a fixed slot instead of letting it interrupt you at random. A short weekly check and a slightly longer monthly one is enough for most situations.
- Weekly: ten minutes to check what came in, what went out and what is next.
- Monthly: update the plan for anything that changed and confirm the priority.
- Every few months: review contracts, subscriptions and insurance.
- After any change in income or costs: redo the overview rather than adjusting in your head.
- Between those moments, leave it alone.
A BAD WEEK IS INFORMATION
Plans slip. A week that went wrong tells you where the plan was unrealistic, which is useful, and the fix is usually to change one number rather than to start again.
Steadiness matters more than accuracy here. A rough plan you check every week beats a precise one you abandon.
WHEN TO GET EXTRA HELP
Some situations need more than a better overview. Getting help early usually leaves more options open, and it is a normal step rather than a last resort.
Consider getting support if any of these describe your situation.
- Your income does not cover your essential costs even after a full review.
- You are behind on rent, mortgage, energy, health cover or taxes.
- Creditors or collection agencies are actively contacting you.
- You are borrowing to make payments on other borrowing.
- Money worries are affecting your sleep, work or health.
- You have opened the overview several times and cannot see a way through.
WHERE TO GO
Use official debt advice, municipal services or a qualified adviser in your country. What is available and what they can arrange differs by place, which is exactly why local advice beats general advice.
If money pressure is affecting your health, treat that as its own reason to speak to someone. Our help page lists the kinds of support worth looking for.
PRACTICAL MONEY CONTROL CHECKLIST
Work through this in order. Tick what is done and leave the rest for the next session rather than trying to complete it in one sitting.
Anything you cannot answer yet is simply your next task.
- One place chosen where your money information lives.
- Current balance of every account written down.
- Lowest realistic monthly income noted, with payment dates.
- Two or three months of outgoings listed in full.
- Annual costs divided by twelve and added in.
- Every cost marked as essential or open to change.
- Payments ranked by consequence rather than by amount.
- Anything you are behind on written down plainly.
- One monthly plan on a single page, built around payment dates.
- Automatic payments timed just after income arrives.
- One buffer line included, however small.
- Any leftover amount given one job.
- A weekly ten minute check booked in.
- Official help contacted if the numbers do not meet.
FREQUENTLY ASKED QUESTIONS COME NEXT
Short answers to the questions that come up most when money feels out of control.
FREQUENTLY ASKED QUESTIONS
General information only. Rules, support and consequences differ by country and by situation.
HOW DO I GET CONTROL OF MY MONEY WHEN I FEEL OVERWHELMED?
Start by making the situation visible rather than by making decisions. Write down your balances, your next income and the payments due before it. Overwhelm usually drops once the numbers are on one page, because you are dealing with a list instead of an unknown. After that, take one step at a time in the order set out above.
WHAT SHOULD I DO FIRST WHEN MY FINANCES FEEL OUT OF CONTROL?
Open your accounts and read them. It sounds too simple, but avoidance is what keeps most people stuck, and everything else depends on knowing the real figures. If opening the app is the hard part, do that alone as the first task and build the overview on another day.
HOW CAN I MANAGE MY MONEY WHEN I DO NOT HAVE ENOUGH INCOME?
When income does not cover essential costs, budgeting alone will not close the gap and it is not meant to. Check whether allowances or local schemes apply to you, contact creditors before payments fail to ask about temporary arrangements, and get your situation reviewed by official debt support in your country. Look at whether any additional income is realistic, but treat outside support as the main route rather than the last one.
HOW OFTEN SHOULD I REVIEW MY FINANCES?
A short weekly check and a longer monthly update works for most people, plus a full review whenever your income or costs change. There is no correct frequency. Checking often enough to catch problems early matters more than any particular schedule, and once the information is written down each check takes minutes.
WHAT IF I HAVE DEBT AND FEEL COMPLETELY OVERWHELMED?
Put every debt into one overview before deciding anything, including the creditor, the amount, the monthly payment and any deadline. Which debt should be handled first depends on the type of debt, the creditor, the consequences of nonpayment and the rules where you live, so it is not something to decide from a general rule. If you are behind on payments or being contacted by collectors, speak to official debt advice or a qualified adviser in your country.
TURN THE OVERVIEW INTO REAL NUMBERS
The free Money Reset puts your income, fixed costs and spending into one picture in a few minutes, so you can see what is left and what needs attention first. Everything stays on your own device.
Some links on this page may be affiliate links. If you use one, we may earn a small commission at no additional cost to you. Not every link is an affiliate link, and we never take gambling or betting partnerships. Read the full disclosure
This article is general information and education. It is not personal financial, tax or legal advice, and rules differ by country. If you have serious payment problems, contact official debt support or a qualified financial adviser near you.
NEXT STEP
Once the overview exists, the next question is usually where the everyday money goes. The Spending Check answers that in a few minutes.
OPEN THE SPENDING CHECKCONTINUE FROM HERE
Two natural next steps, whichever chapter you are working on.
READ NEXT
HOW TO GET YOUR FINANCES BACK ON TRACK
The full guide: overview, bills, debts and a plan you can keep.
HOW TO ORGANISE YOUR DEBTS WHEN YOU FEEL OVERWHELMED
One overview, clear priorities and a plan that matches your income.
HOW TO LOWER YOUR MONTHLY EXPENSES
Go through each recurring bill and find the room that repeats every month.